ACA Open Enrollment 2027: New EDE Verification Rules Agents Need to Know
By October 12, 2026, CMS requires Enhanced Direct Enrollment platforms to systematically enforce consumer identity proofing for higher-risk cases and consumer authorization for every application submitted through the EDE agent and broker pathway. With 76% of active HealthCare.gov plan selections receiving agent or broker assistance during OEP 2026, the change touches a major part of the ACA enrollment ecosystem.
ACA Open Enrollment for 2027 coverage begins November 1, 2026. But an important change to the agent-assisted enrollment infrastructure is scheduled to arrive almost three weeks earlier.
CMS has directed Enhanced Direct Enrollment partners to implement new consumer identity-proofing and agent or broker authorization requirements no later than October 12, 2026. This is not the introduction of EDE itself — it is a change in how consumer identity and agent authorization are enforced inside the EDE agent and broker pathway.
76%
of active HealthCare.gov plan selections in OEP 2026 involved agent or broker assistance
Oct 12
CMS deadline for EDE partners to put the new controls into production
15 min
maximum lifespan of a one-time authorization link or passcode
Source: CMS, August 2026 guidance and OEP 2026 Marketplace data.
For ACA agencies, web-brokers, publishers and lead buyers, that makes the change relevant well beyond the compliance department. It affects the practical journey from consumer inquiry to agent contact, verification, authorization, application and enrollment.
Why EDE Matters to the ACA Market
Consumers do not have to complete every Marketplace enrollment directly through HealthCare.gov. Approved enrollment partners can offer Marketplace application and enrollment functionality through their own websites, and an approved EDE environment can support the eligibility application, plan enrollment and certain post-enrollment functions while integrating with the Federally-facilitated Exchange.
Agent involvement remains significant. During Open Enrollment 2026, 76% of the 10.8 million active HealthCare.gov plan selections involved agent or broker assistance, according to CMS. That figure identifies agent or broker assistance rather than the enrollment channel used, so it does not mean 76% of enrollments happened through EDE specifically. But it does show how central agents and brokers remain to the Marketplace customer journey.
What Exactly Is Changing for OEP 2027?
CMS announced EDE Change Request 109 in May 2026 and released detailed guidance in August. The central requirement is straightforward: for applications or enrollments submitted through the EDE agent and broker pathway, EDE platforms must systematically enforce consumer authorization. In certain cases classified as higher risk, the consumer must also successfully complete identity proofing before authorization can be collected.
“All applications using the EDE agent and broker pathway require consumer authorization — regardless of whether the application is classified as high or low risk.”
If authorization has not been completed, the agent or broker will be blocked from proceeding with relevant application or enrollment actions. That gives agencies only a short window between the October 12 implementation date and the November 1 start of Open Enrollment.
CMS Is Using a Risk-Based Verification Model
Not every consumer will encounter exactly the same verification process. CMS created high-risk and low-risk categories.
Higher risk
- New consumer application, including a different coverage state
- Active enrollment with a net monthly premium of $30 or less after APTC, excluding standalone dental
- Consumer working with a different or new agent or broker
Identity proofing first, then agent authorization.
Lower risk
Applications that do not trigger those criteria are treated as lower risk. Identity proofing may not be required, but the consumer still has to authorize the agent before the agent can proceed.
Authorization always applies.
The distinction matters. Identity proofing is risk-based. Agent authorization applies to every EDE agent-assisted application. Those two should not be confused.
One-Time Codes and Links Become Part of the Enrollment Journey
For lower-risk applications, an EDE platform may use a lighter authorization process. CMS allows mechanisms such as a one-time passcode, a one-time confirmation link, or another similar method to obtain authorization from the consumer.
The technical detail that should get marketers’ attention is the time limit. CMS requires these links or passcodes to be single use and to expire within 15 minutes of generation. EDE platforms also cannot send more than three authorization or identity-proofing notifications within 24 hours for the same agent-user and application combination.
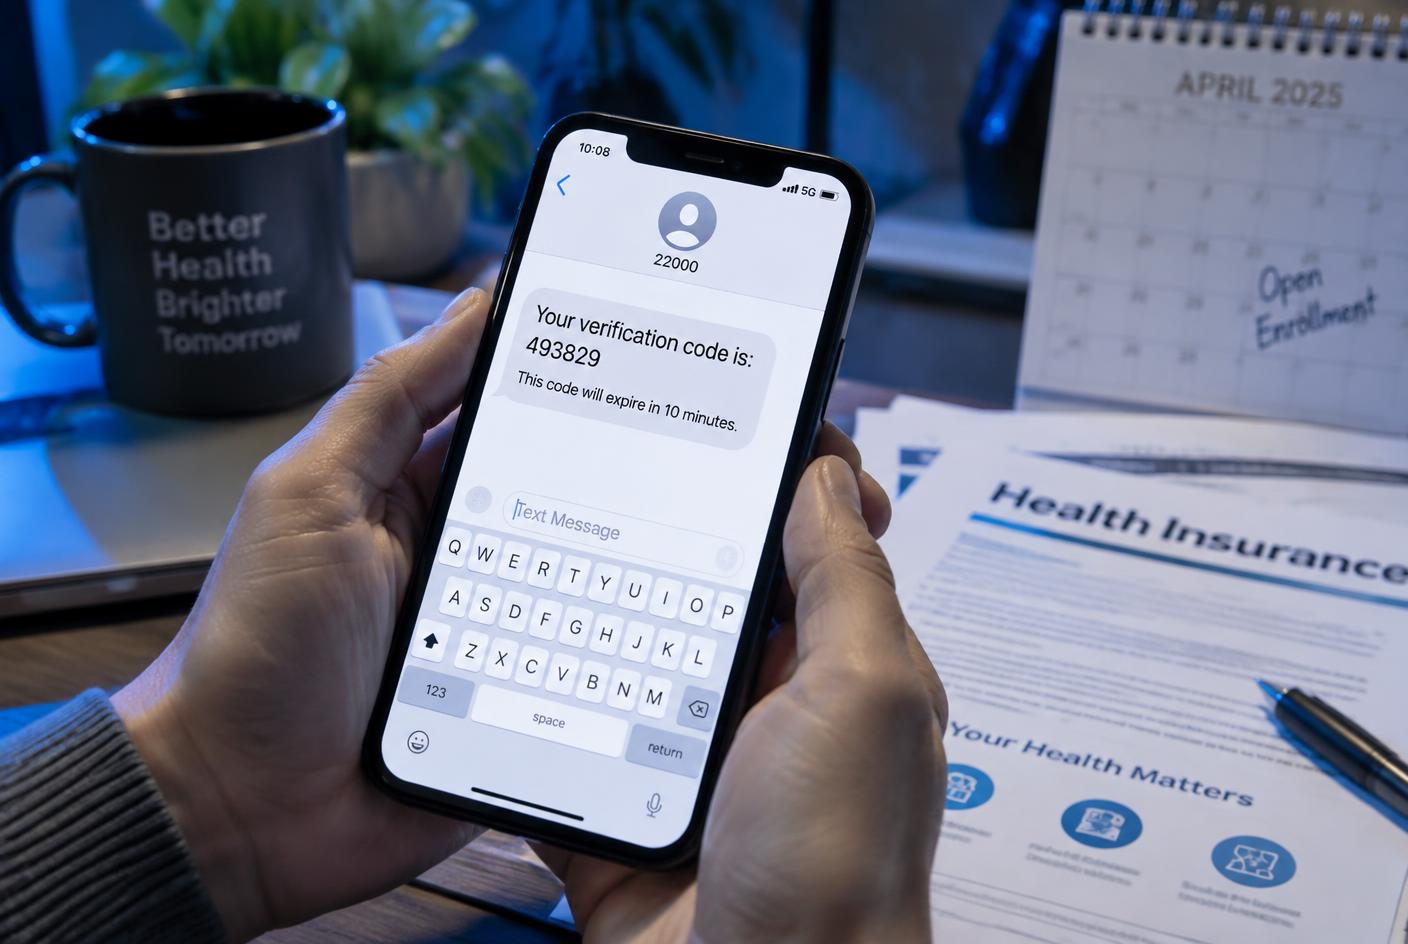
That does not mean an ACA lead expires after 15 minutes. It means the authorization credential itself has a 15-minute life once generated. Operationally, though, the requirement reinforces one idea: the consumer needs to remain actively involved in the enrollment process. An agent working with an engaged consumer who has their phone and email nearby is operating under very different conditions from an agent trying to revive an old record whose owner barely remembers submitting a request.
Accurate Contact Information Is Becoming Even More Important
CMS says new consumers must provide a phone number and email address that they themselves can access for identity proofing and authorization. CMS also explicitly states that agents and brokers must not substitute their own personal, company or professional phone number, email address or mailing address for the consumer’s information.
For ACA acquisition teams, that means data accuracy affects more than contact rate. A mistyped email address used to mean “this lead may be harder to contact.” Under a verification-based process, it can also mean “this consumer may have difficulty completing an authorization step.”
Consent and EDE Authorization Are Not the Same Thing
This is one of the most important compliance distinctions in the whole update. The new EDE authorization process does not replace the existing requirement for agents and brokers to obtain and document consumer consent. CMS explicitly says consumer consent must still be collected before an agent accesses consumer information or searches for the consumer on an EDE platform.
Consumer consent
The consumer’s permission for an agent or broker to access their information and provide Marketplace assistance. Collected and documented by the agent before any EDE search.
EDE agent authorization
A platform-level control authorizing the agent to take application or enrollment actions through the EDE pathway. Enforced by the platform itself.
That distinction is particularly important for organizations purchasing ACA leads from outside marketing sources. The fact that a consumer completed a web form does not eliminate the agent’s Marketplace consent obligations.
Existing Clients Will Also Matter
Agencies might assume the biggest effect lands on new ACA prospects. That is not necessarily the case. CMS says agent and broker authorization should generally be obtained every plan year, including for consumers who already have an account on the EDE platform. Once provided, authorization generally remains valid for that plan year unless the consumer authorizes a different or new agent.
Identity proofing works somewhat differently. CMS says identity proofing may remain valid on an EDE platform when the consumer has an account and the verification credentials remain associated with it. Without that account structure, identity proofing generally needs to be reconfirmed for each coverage year. Some EDE partners may allow agents to work through identity proofing with existing clients before Open Enrollment begins — but most existing consumers are still expected to reauthorize their agent for the new plan year.
ACA Lead Quality Now Has Another Layer: Enrollment Readiness
Consumer A submits an inquiry and answers the phone almost immediately. They recognize the request, can access their phone and email, and are ready to continue.
Consumer B completed a form days earlier, barely remembers it, cannot access the email address used, and did not expect an insurance conversation.
Both records may count as leads. Their ability to progress through an interactive enrollment workflow is very different.
The ACA Funnel Should Be Measured Further Downstream
A campaign can produce an excellent CPL and still produce weak business economics. OEP 2027 gives agencies another reason to measure the funnel beyond raw lead volume. A useful acquisition path now looks more like this:
- Consumer inquiry
- Contact
- Qualified conversation
- Required verification
- Agent authorization
- Application
- Plan selection
- Effectuation
Traffic Source A may generate inexpensive leads with poor contact rates. Traffic Source B may cost more but produce consumers who are still actively engaged when an agent calls. Comparing CPL alone might favour Source A; comparing qualified conversations, authorization completion and enrollment could produce a very different picture.
Real-Time Consumer Intent Becomes More Operationally Useful
Speed-to-contact was already important before these changes. What the EDE requirements do is give active consumer engagement greater operational relevance. Shortly after someone requests ACA assistance, the consumer is more likely to remember the advertisement, their phone is likely nearby, they may still be reviewing coverage, they usually have access to the email account used, and the original reason they started shopping is still fresh.
That does not guarantee an enrollment. It does make the transition between digital inquiry and interactive enrollment easier than attempting the same process after consumer interest has cooled. For organizations buying ACA leads or live calls, that is one reason to distinguish fresh consumer-initiated demand from older data.
The 2027 Compliance Environment Is Changing on the Marketing Side Too
EDE authorization is not the only ACA development marketers should watch. CMS’s 2027 Notice of Benefit and Payment Parameters final rule became effective July 20, 2026 and includes stronger standards governing Marketplace marketing by agents, brokers and web-brokers.
CMS identified examples of prohibited marketing practices including cash or cash-equivalent inducements to enroll, falsely suggesting that consumers will always qualify for zero-dollar insurance or zero-dollar premiums, and misrepresenting enrollment deadlines or timelines. CMS also finalized requirements related to producing marketing materials for monitoring, audit and enforcement.
That means compliance should be considered across the whole acquisition chain: creative, advertisement, landing page, consent, lead, agent and enrollment. A company cannot judge traffic quality solely by how many forms an advertisement generates — it should also know how that demand was created.
Why Lead Buyers Need Better Source Transparency
A consumer may have come from a search advertisement, a social campaign, an inbound call, a comparison website, a web form, an affiliate publisher or another acquisition source. The source itself is not automatically good or bad. What matters is whether the consumer journey was clear.
The buyer should understand the message used to generate the inquiry, the consent collected, when the consumer responded, what information the consumer supplied and what expectation was established about subsequent contact. Those details become more important when the consumer must actively participate later in the enrollment workflow. A lead that reaches the CRM with no meaningful source context makes optimization difficult.
Why Publishers Should Care About What Happens After the Lead
Publishers frequently optimize around traffic, CTR, conversion rate and CPL. Those metrics remain useful, but lead buyers ultimately care about what happens downstream. If consumers repeatedly submit forms and then fail to recognize the agent call, provide inaccurate contact information, or expect an unrelated benefit instead of insurance assistance, the publisher has a problem.
The objective is not simply to generate the form. It is to generate an informed consumer who can continue through the insurance journey.
What ACA Agencies Should Have Ready Before October 12
The new EDE requirements are scheduled to reach production before Open Enrollment rather than during it. Agencies using EDE should understand how their specific platform intends to implement identity proofing and authorization, because CMS notes individual EDE implementations may differ while still following the federal technical requirements.
- The end-to-end enrollment workflow inside your EDE platform
- Which consumer communication channels carry codes and links
- How agents explain authorization on the call
- What happens when identity proofing fails
- How existing clients will be reauthorized for the plan year
- How reporting separates verification failures from ordinary sales losses
OEP 2027 Key Dates
| Date | What happens |
|---|---|
| October 12, 2026 | CMS deadline for EDE partners to enforce identity proofing and agent authorization |
| November 1, 2026 | Federal Marketplace Open Enrollment begins |
| December 15, 2026 | Deadline for coverage starting January 1 |
| January 15, 2027 | Open Enrollment ends |
| February 1, 2027 | Coverage generally starts for consumers enrolling between December 16 and January 15, assuming required premiums are paid |
State-based Marketplaces can have their own operational details, so insurance organizations should verify the requirements applicable to each market they operate in.
What This Means for ACA Lead Generation in 2027
The central change is not that ACA leads suddenly need to be generated differently. It is that low-quality acquisition becomes easier to expose downstream. A consumer who did not knowingly request assistance may struggle when asked to actively authorize an agent. A consumer with inaccurate information may struggle to verify themselves. An old record may have less active engagement when verification is required.
Optimize for consumers who can continue the journey, not just consumers who can complete the form.
Turn ACA Consumer Intent Into Real Conversations
Freedom Marketing Group helps insurance organizations connect with consumers through ACA acquisition solutions designed around active consumer interest and real-time opportunities. In an enrollment environment where consumer participation increasingly matters, your acquisition strategy should focus on more than filling a CRM — it should create a cleaner path from consumer inquiry to a qualified insurance conversation.
Information in this article is based on CMS guidance published in 2026 and HealthCare.gov published Open Enrollment dates, and is provided for general informational purposes only. Freedom Marketing Group is not affiliated with or endorsed by Medicare, CMS, HealthCare.gov or any government agency. Nothing here guarantees enrollment or sales results, and agencies should confirm requirements with their own EDE platform and compliance counsel.
Frequently Asked Questions
See how our ACA live transfers and health insurance leads are delivered, screened and routed to your agents.
Related reading
- ACA Open Enrollment 2027 Starts November 1: 7 Changes Agents Can't Afford to MissACA · 11 min read
- ACA Open Enrollment 2027: Why Speed to Consumer Will Matter More Than Lead VolumeACA Insights · 8 min read
- The ACA Market in 2026: What's Changing and Where the Next Growth Opportunity LiesACA · 11 min read